All Categories
Featured

Benefits of Diversified Asset Allocation in 2026
Table of Contents
Overall, we expect real GDP growth to speed up from an average rate of 1.1% growth over the 4th and very first quarters to approximately 3.0% growth in the second and third quarters and after that slow down to about 1.5% growth in late 2026. Stronger development could be extended into the fourth quarter if the federal government passes even more fiscal stimulus before the mid-term elections.
With the start of 2026, investors are when again turning their focus to positioning portfolios for the year ahead. Expecting which asset classes might offer the most attractive returns over the coming twelve months, and identifying the dominant styles most likely to affect markets, is more crucial than ever. The global economic backdrop has shifted significantly compared to this time in 2015, prompting renewed concerns about where opportunities and threats will lie in 2026, along with which possessions are likely to outshine or underperform.
Top Foreign Capital Trends within GCC Economy: US growth faces difficulties due to tensions in its institutional structure and demanding assessments. The divergence between financial policies and inflation highlights the requirement for adequate.In this context, will keep their relevance, although they will need a. present fascinating chances to diversify equity portfolios, with attractive valuations.: preferred by more flexible main banks and a weaker dollar, they can benefit,.: continue to combine as a crucial component of portfolios, with acting as long-term worth chauffeurs and levers for structural changes such as decarbonization and digitization.
The ought to use brand-new entry points in the 2nd half of 2026.: opportunities in the growing Asian technological environment. In local currency debt, we prefer Central and Eastern Europe, selective regions of Latin America (Colombia, Brazil) and Asia (India, Philippines, and Korea) for bring and valuation.: significant chances that prefer value designs, in addition to momentum in Latin America and Eastern Europe, and selectively in Asia, in sectors connected to digital properties.
Steady rates, more flexible financial policies and greater market opportunities define the course for 2026. Stabilization of the international economy, an enhancement in business profits and a boost in chances in equity and fixed earnings. Set income: top quality as a source of earnings and portfolio stability.: the return of market breadth.
Strategies to Maximise Foreign Capital Potential in 2026
The is being limited, at a time when inflation in the EU is close to the ECB's target and is harder to control in the US, around 3%., in a market situation that marks down that the ECB will postpone the lowering of intervention rates., with appealing spreads, as the best way to benefit from present levels, and sees prospective for revaluation in.: its development will be conditioned by the rebound of the expected profits for 2026, specifically in United States tech companies, fiscal stimuli in Europe and the normalization of global trade.
: will continue to sustain financier optimism and open opportunities in emerging stock markets, innovation customer and health midcaps, and in infrastructure and energy shift in personal markets.: the "Stunning Seven" can still support the marketplace due to their earnings power and steady bet on AI, however leadership starts to show more dispersion among large tech companies.: expected capex rebound due to reindustrialization and fiscal margin, with possible to continue standing out in defense, energy and finance and to include delayed sectors for a more comprehensive rally.: macro tailwind and really inexpensive valuation compared to the US (40% discount rate) indicate possible outperformance in 2026.: the divergence in between main banks develops opportunities, however be.: there is space to generate attractive earnings by taking advantage of carry in (CLO AAA and BBB tranches with relative value) and in, as popular sources of repeating profitability.: take advantage of more sensible rates and larger rounds and stays attractive for profitability and low default in spite of steady spreads.
Top Foreign Capital Trends within GCC EconomyKeep a, without recession in the main scenario for 2026. It is expected that, including hedge funds, private credit and real possessions, will play a in investors' portfolios., China increasing its impact in different areas and Europe (especially Germany) trying to become pertinent again.: the chance to use NextGen funds stays appropriate to increase quality development.
The 2026 Middle East Fiscal Projection
The will continue with its "risk management" method and will apply more rate cuts in 2026. Powell's successor might be more inclined to lower rates.: the steepening of the curve is most likely to continue. We preserve our choice for.: high assessments advise caution. The has stood apart however we do not consider it suitable to improve our suggestion on it.

Latest Posts
The 2026 Middle East Fiscal Projection
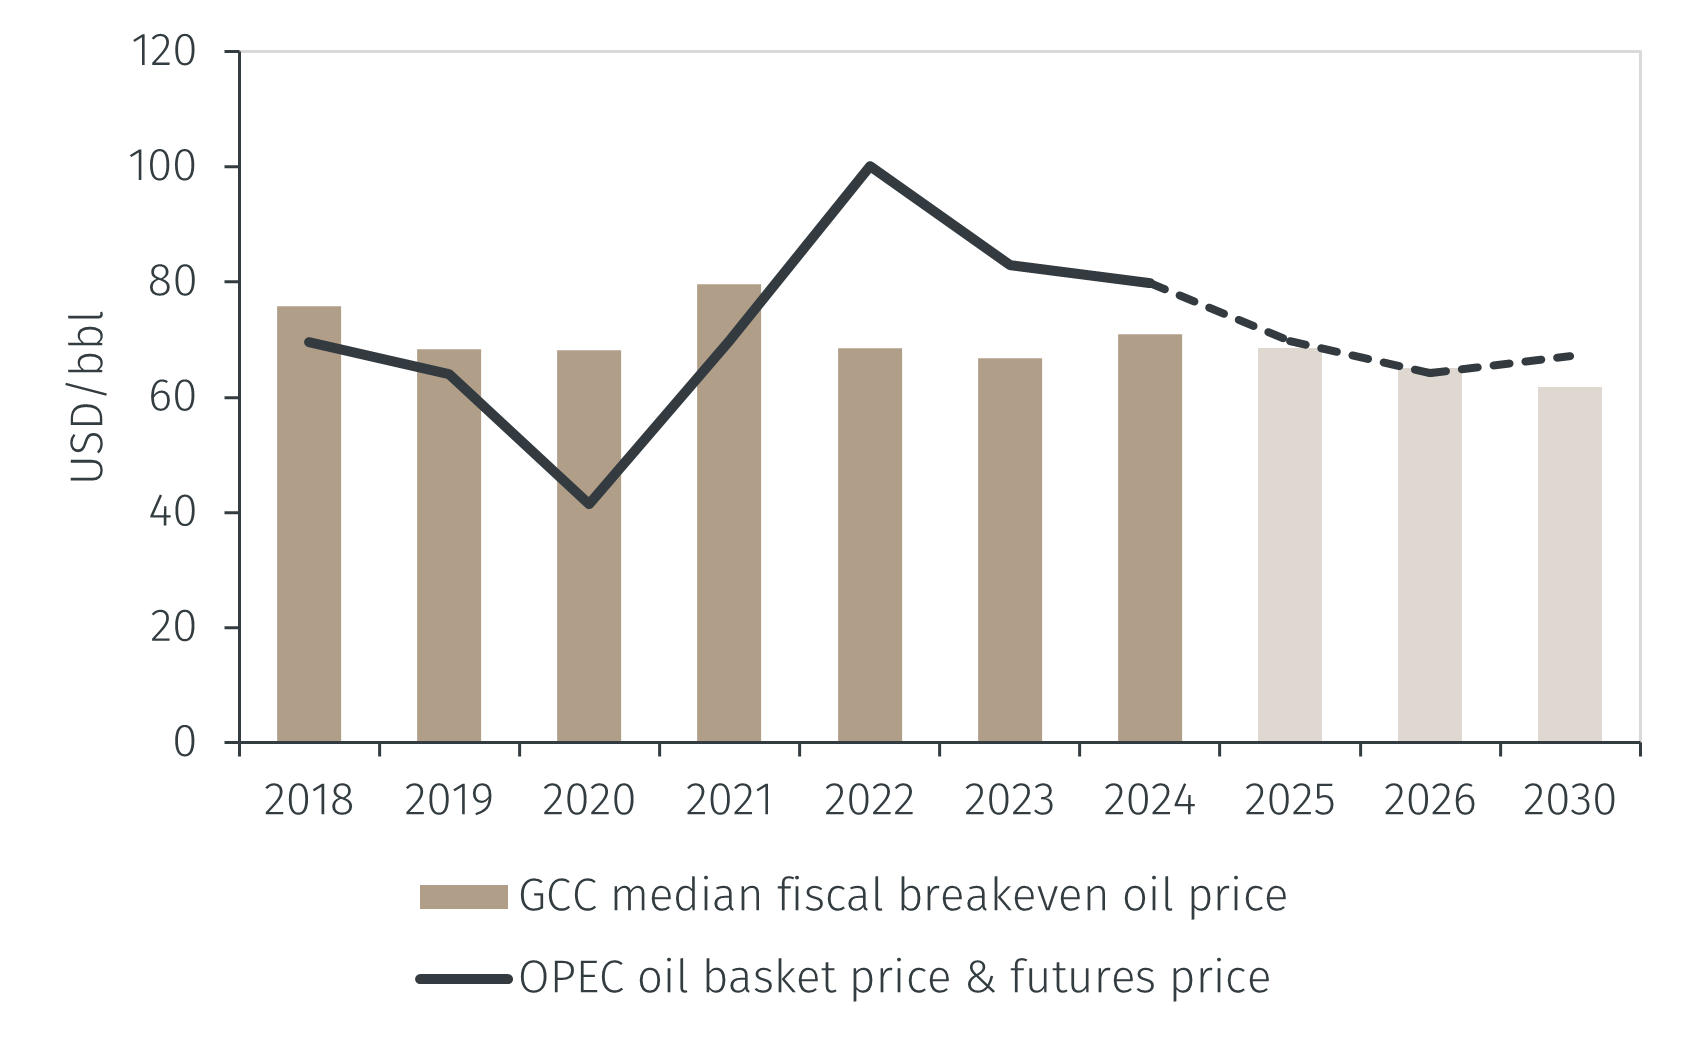
International Capital Opportunities across the Middle East

Can GCC Non-Oil Success Outpace Western Benchmarks?