All Categories
Featured
Driving Non-Oil Success through Strategic Diversification
Table of Contents
Residential or commercial property rates have actually come under pressure after a duration of strong growth, with current information from the Dubai Land Department showing a drop in home loan transactions and cash sales. However, we believe the risk of an enduring migrant outflow and an extreme downturn in the realty sector is low.
As a lasting US-Iran offer takes shape, the fallout from the conflict has tightened up local financial conditions, exposing vulnerabilities through capital outflows, wider bond spreads, and weaker investor belief. The majority of GCC sovereigns bring reasonably little debt and funding risks are for that reason limited in the UAE, the reserve bank's liquidity management has relieved instant issues.
That stated, Bahrain has actually been able to depend on support from neighbours, consisting of Saudi Arabia and the UAE, and it successfully raised $1bn from an oversubscribed sovereign bond sale this month, marking the very first offering from the region since the war started. High-frequency fiscal information highlight the strain on local public finances from the dispute.
The Future Business Landscape in the GCC
In Saudi Arabia, the deficit spending more than doubled to SAR125.7 bn, or about 9% of GDP in Q1, driven by a decrease in oil income and a surge in costs, especially on subsidies, reflecting contingency outlays tied to the regional environment and an acceleration of Vision 2030 spending. In Qatar, the crisis brought oil and gas earnings to a halt, swelling the deficit spending to the biggest given that 2017.
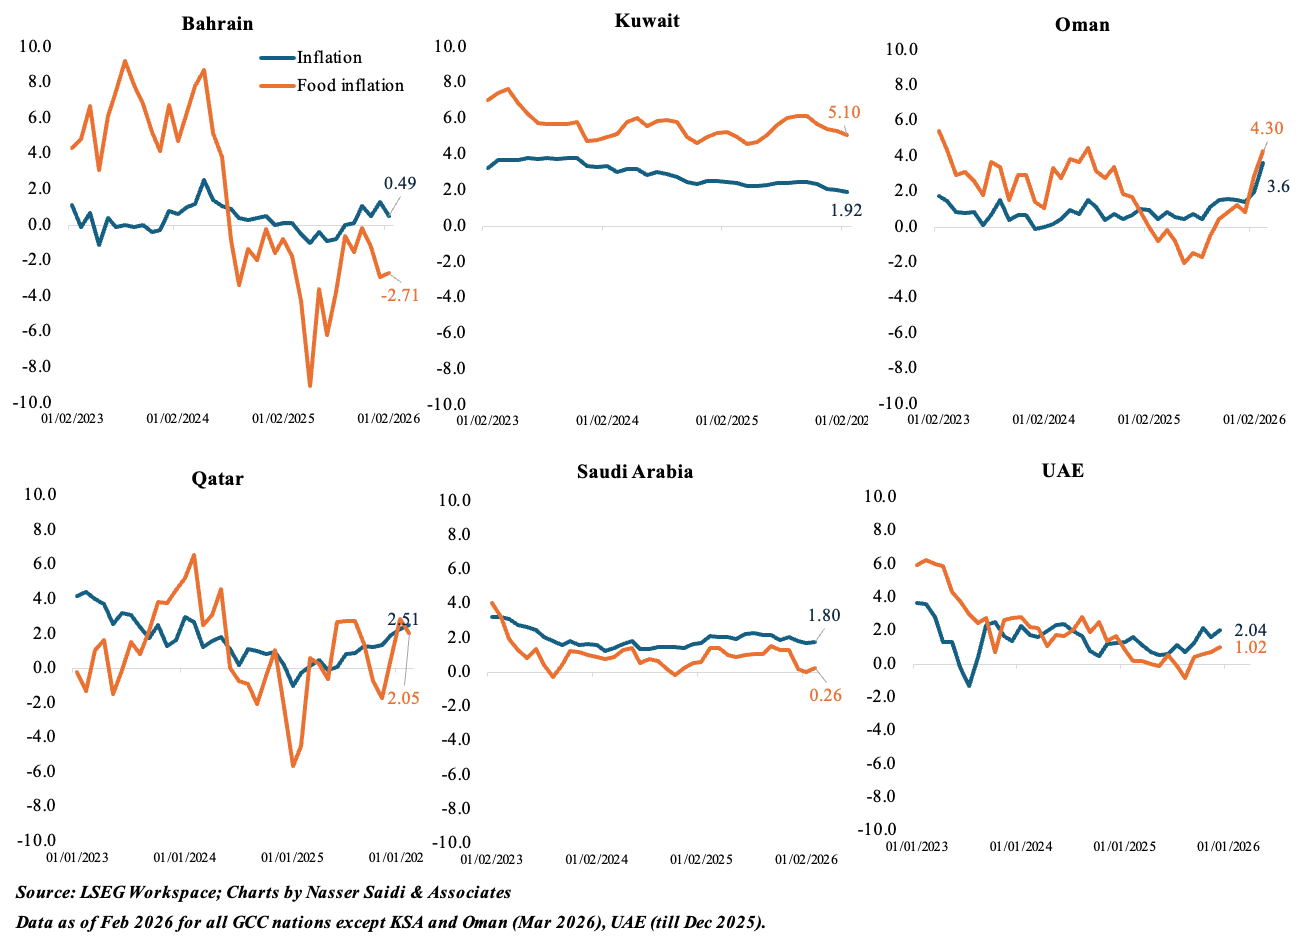
GCC inflation dynamics stay unequal, with food rates the primary source of upward pressure and inflation in this category conditioning in Kuwait, Oman and Qatar. By contrast, food inflation remains fairly controlled in Saudi Arabia, most likely reflecting the mitigating result of its bigger domestic food production base and greater supply-chain durability.
We continue to see price pressures as mostly transitory instead of indicative of a sustained inflationary cycle. Accordingly, we expect average inflation to ease to 2.1% y/y in 2027 as momentary supply-side pressures dissipate. With near-term inflation raised and transit through the Strait likely set to resume gradually, we expect the United States Federal Reserve to keep rate of interest on hold until December, and local rate policies to do the same.
We expect Iran's GDP to shrink by 10.8% this year (we anticipate a 9.4% contraction 3 months ago). Oil production and exports, which offer necessary earnings and FX inflows, have been reduced by the United States marine blockade, while non-oil activity has been severely struck. In Iraq, oil exports have collapsed to a drip and we're anticipating GDP to contract by around 22% this year, with a sharp 33% rebound in 2027 as oil exports normalise.
By contrast, Syria continues to reintegrate into the global economy after more than a years of civil war. We anticipate GDP development to average 9.6% over 2026-2027, supported by restored financial investment, especially in banking and energy, monetary reforms, and the steady reopening of local trade links.
Emerging Stock Market Trends for 2026
The World Bank has slashed its 2026 development forecast for Middle East economies, saying overall GDP growth in the area is anticipated to slow from an approximated 3.6% in January to 1.8% for 2026. The closure of the strategic Strait of Hormuz, and destruction of energy and public infrastructure, had interfered with markets, increased monetary volatility, and damaged the 2026 growth outlook, the World Bank Group said in its Economic Update for the Middle East, North Africa, Afghanistan and Pakistan.
The April 2026 World Bank's Macro Poverty Outlook forecasts that the area's aggregate (excluding the Iran) GDP development will decelerate to 1.8 percent in 2026, below 4.0 percent estimated for 2025. The 2026 forecast has been devalued by 2.4 portion points considering that the January projections, showing the unfavorable effects of the continuous dispute.
Key Drivers Influencing Gulf Market Forecasts for 2026Saudi Arabia: Projection was downgraded by 1.2 portion points considering that January. Growth is now expected to slow from 4.3% in 2025 to 3.1% in 2026, keeping in mind that Saudi Arabia's outlook remains the strongest among Gulf economies. United Arab Emirates: Growth projection for the UAE has actually fallen by 2.7 portion points considering that January.
Qatar: Notably, development forecast for the Qatari economy has seen a sharp decline of 11.0 portion points since January. The economy is now anticipated to tape a contraction of 5.7%, down from an approximated development of 5.3%, due to serious blockage to melted gas materials. Qatar is an essential player in the global energy market, with a global market share of melted natural gas (LNG) products varying in between 20% and 21%.
Kuwait relies totally (100%) on the Strait of Hormuz to export its unrefined oil and derivatives. Closing the strait would imply a complete shutdown of the nation's financial lifeline, right away halting income inflows to the state budget. Bahrain: Growth forecast for Bahrain's economy has declined by 1.8 portion points given that January.

Latest Posts
The 2026 Middle East Fiscal Projection
International Capital Opportunities across the Middle East

Can GCC Non-Oil Success Outpace Western Benchmarks?