All Categories
Featured

Strategies for Asset Allocation in 2026 Global Markets
Table of Contents
Oct 2019 Walid Majdalani, Head of Investcorp Private Equity MENA business, details the appealing chances of investing in GCC Infrastructure, driven by the region's growth and federal government efforts.
Diversity is attain a well balanced economy,, Diversity visions and methods exist. The general Global EDI is composed of tracking.
Benefits of Expanding Industrial Ventures across Middle EastFor non-diversified countries, when price of the commodity falls, there is a considerable decline in government profits, public costs, bank account balance and international reserves: more volatility. The (including major product exporters, not restricted to just oil) over the, across 25 signs (consisting of three digital indicators). North America, Western Europe and East Asia Pacific nations leading EDI ratings for many years.
Although structural reforms and diversity efforts undertaken by the GCC impacted MENA's local scores positively, it still lags five other regional groups., with the top 10 nations having less than a 10-point distinction in scores (suggesting the strength of diversity)., together with 4 upper-middle income (China, Mexico, Turkey and Thailand) and one lower middle-income country (India, ranked 20th, driven by its services export boom).
Among the e. countries ranked 51 to 70, the performance of Moldova, Indonesia, Armenia and Honduras stick out (when comparing 2024 vs 2000). years, provided sped up diversity strategies of lots of oil-exporting countries. posted a consistent improvement due to a combination of reduced reliance on fuel exports, lowered exports concentration and a change in the composition of exports.
Key Factors Shaping Gulf Market Outlooks by 2026
with oil exporters having the most affordable scores (though specific country-specific performance has actually differed with time). Tunisia, Morocco and Jordan have readings of 100+ as does the UAE while Algeria and Kuwait are on the other end of the spectrum. Across all areas, the median rating is the for both 2000 and 2024, and the greatest in The United States and Canada.
In 2024, the (China was among the top ranked, while Mongolia's rating worsened compared to 2000)., but more to do with a "levelling up" at the bottom instead of an enhancement among the leading nations. By comparing the (height of the blue box), least irregularity is seen in South Asia in 2000 and the most in the MENA area (with variance most likely driven by the dichotomy within the area in between the resource-heavy states (e.g.
Sub-Saharan African countries represent around one-third of the total, followed by Latin America and the Middle East (the latter 2 together representing over 40% of the total). Consisting of, there has been an (from 90.3 in 2000-04 to 92.6 and 92.3 in the 5 years pre- and post-pandemic ).
and ranked greater than others; UAE is up more than 45 places in 2024 compared to 2000 while Qatar climbed up 24; both Saudi Arabia and Oman increased 17 ranks during the duration. The caught or even worse off nations are some parts of Latin America and Sub-Saharan Africa where structural improvement has actually stalled.
shows a considerable boost in average EDI scores from 86.8 in 2000-04 to 92.6 in 2020-24, (up more than 10 points in the preliminary duration versus 2020-24). with UAE surpassing in the trade sub-index (supported by recent bilateral trade contracts & non-oil exports push). vs its pre-pandemic reading (partially offered the surge in medium & state-of-the-art manufacturing data).
Building Sustainable Investment Portfolios with Arabian Assets
Its diversity metrics have stagnated, revealing the least enhancement between the preliminary (2000-04) and last (2020-24) referral periods., despite the headwinds of OPEC+ production cuts. A robust non-hydrocarbon expansion was supported by the GCC's robust domestic demand (supported by a strong project pipeline and implementation) and strong services sector performance.
Kuwait and Saudi Arabia clocked in a boost in non-hydrocarbon income, "mainly showing non-hydrocarbon tax base growths and income collection effectiveness enhancements", according to the IMF. In the current geopolitical environment identified by heightening, it remains in the best interests of commodity dependent nations to diversify its export base, exports and trade partners.
Sub-Saharan African countries represent around one-third of the total, followed by Latin America and the Middle East (the latter 2 together representing over 40% of the total). Consisting of, there has been an (from 90.3 in 2000-04 to 92.6 and 92.3 in the five years pre- and post-pandemic ).
and ranked higher than others; UAE is up more than 45 locations in 2024 compared to 2000 while Qatar climbed 24; both Saudi Arabia and Oman increased 17 ranks throughout the period. The trapped or worse off nations are some parts of Latin America and Sub-Saharan Africa where structural improvement has actually stalled.
Strategies for Asset Diversification for 2026 World Markets
reveals a considerable boost in average EDI ratings from 86.8 in 2000-04 to 92.6 in 2020-24, (up more than 10 points in the initial duration versus 2020-24). with UAE exceeding in the trade sub-index (supported by current bilateral trade agreements & non-oil exports push). vs its pre-pandemic reading (partly given the rise in medium & modern manufacturing data).
Its diversity metrics have stagnated, showing the least enhancement in between the initial (2000-04) and final (2020-24) recommendation periods., despite the headwinds of OPEC+ production cuts. A robust non-hydrocarbon expansion was supported by the GCC's robust domestic need (supported by a strong project pipeline and execution) and strong services sector efficiency.
Kuwait and Saudi Arabia clocked in a boost in non-hydrocarbon revenue, "mostly showing non-hydrocarbon tax base expansions and income collection performance improvements", according to the IMF. In the existing geopolitical environment defined by intensifying, it remains in the finest interests of product reliant countries to diversify its export base, exports and trade partners.

Latest Posts
The 2026 Middle East Fiscal Projection
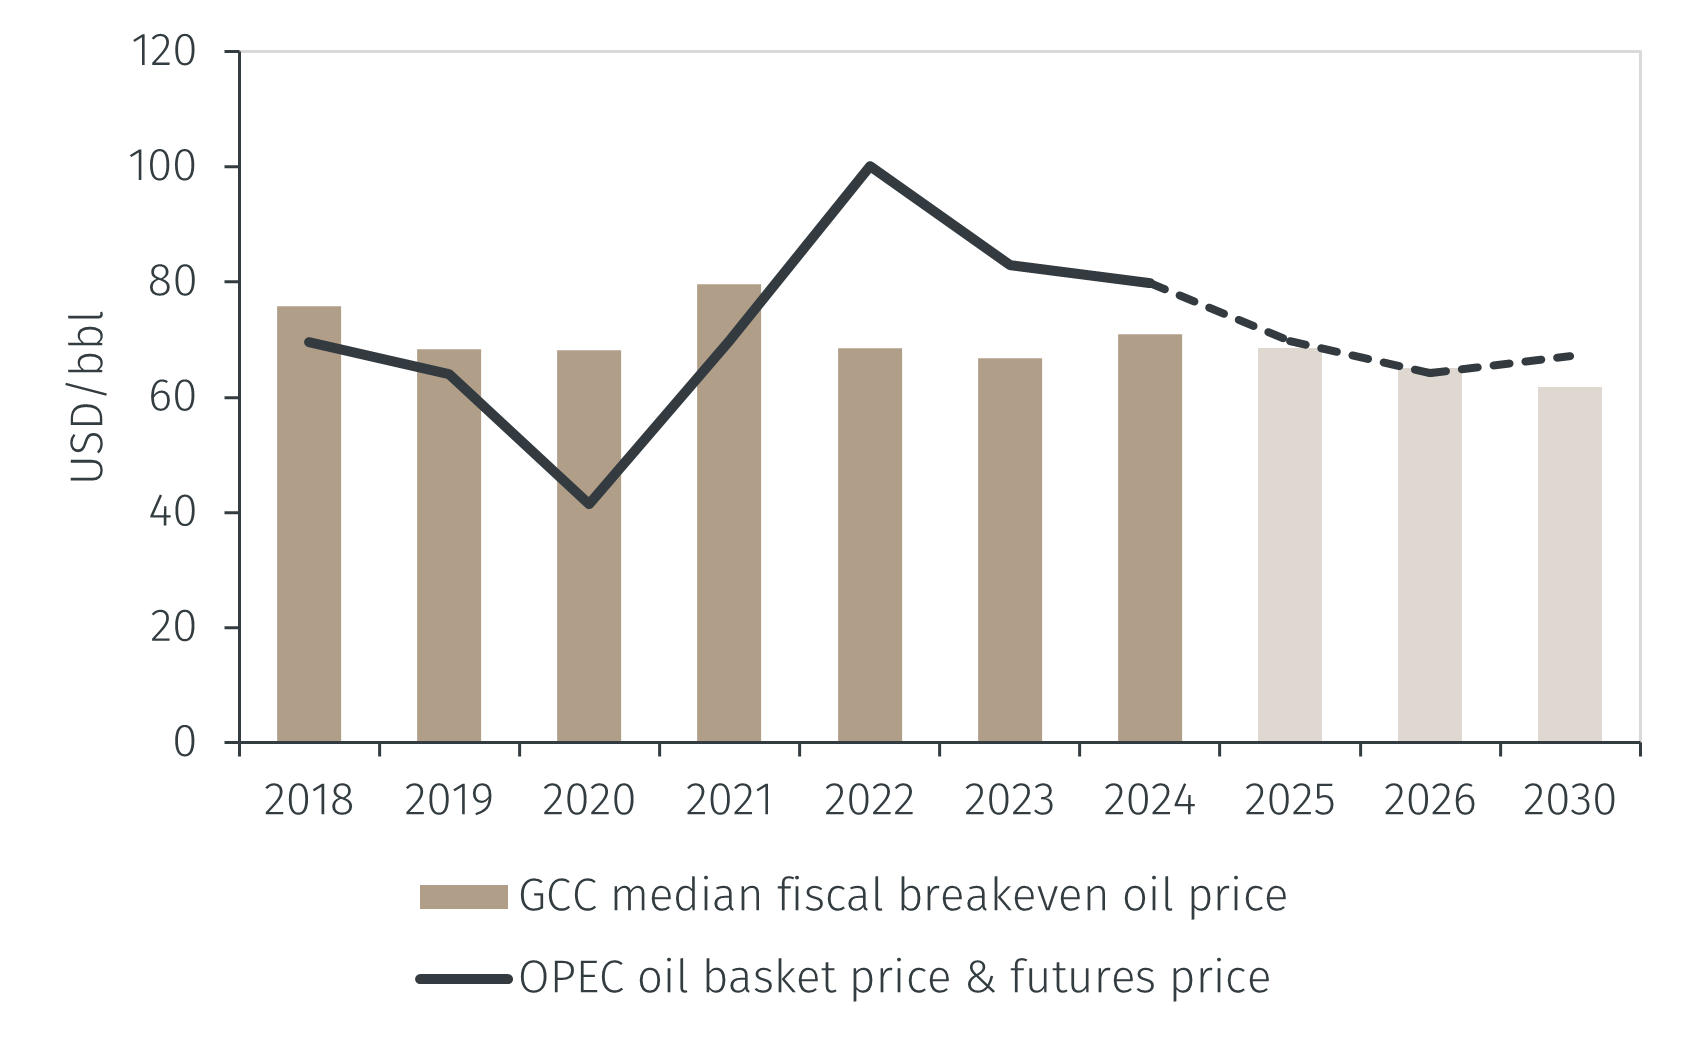
International Capital Opportunities across the Middle East

Can GCC Non-Oil Success Outpace Western Benchmarks?