All Categories
Featured
Upcoming Middle East Investment Shifts for 2026 Global Markets
Table of Contents
In many cases, they have actually sourced products and basic materials required for important procedures from a minimal number of countries. With massive industrialisation now on the program, these vulnerabilities are enhanced. Disruptions have a domino effect due to the fact that the industrial sector is an enabler for other markets. A disruption in the supply chain for transformers, crucial for the power sector, can paralyze electrical power grids and therefore halt everything from the supply of products to transfer systems and factory production.

This cascading impact highlights the urgent requirement for a more durable technique to provide chain management. Fortunately, a toolkit exists to strengthen regional supply chains. Strategic storage, where crucial products such as water, foods items, energy products, metals, and therapeutic items are stocked locally, can buffer versus disruptions. Local production relies on supply chains strength to flourish, but likewise adds to strength by lowering dependence on distant suppliers.
Furthermore, promoting global partnerships, particularly with reputable trading partners, diversifies sourcing alternatives and alleviates threats. These strategies alone are not sufficient, nevertheless. A more comprehensive, holistic method is vital to success. That involves establishing a national supply chain durability framework that effortlessly integrates with the wider industrialisation program. A collaborative governance structure involving the public and personal sectors in tandem is also essential for efficient implementation.
Incentivising and partnering with personal entities can foster financial investment in ingenious solutions for supply chain management. Enacting innovative production policies that promote the adoption of digital tools such as data analytics and expert system can optimise logistics networks, predict possible interruptions, and make it possible for more efficient decision-making. However the technological transformation surpasses simply data.
Western nations like the United States are currently carrying out policies that incentivise the adoption of 3D printing technologies. Studying and adjusting these policies for the Middle East can be a valuable action towards constructing a solid supply chain infrastructure in the GCC. The journey to durable supply chains begins with a shift in state of mind.
Guide to GCC Financial Equity Trends for 2026
By implementing the techniques laid out above, the GCC countries can weave a safeguard for their economic aspirations. They can double down on increased localisation, fostering domestic production of important items and products. This not just lowers dependence on external suppliers but likewise produces jobs and promotes financial growth. A robust and resistant supply chain environment will be the foundation of financial diversification, propelling national visions for development and success.
The 6 countries of the Gulf Cooperation Council (GCC)Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Bahrain, and Omanhave no lack of aspiration. In the past decade, each has actually revealed ambitious nationwide visions targeted at reshaping their economies, unlocking brand-new engines of growth, and placing themselves as international gamers beyond oil.
Co-authored by Basheer Salaytah, Project Leader and long time consultant to federal governments in the Middle East, and Daniel Bristow, Partner and Head of DA's Middle East Practice, the guide provides a grounded and actionable method to assist governments deliver results that last. With over 60% of GCC federal government earnings still tied to hydrocarbonsand as the region faces a growing youth population, unstable worldwide markets, the energy transition, and mounting pressure on the traditional and generous social welfare modelthe region can not afford little or symbolic development.
Upcoming GCC Financial ForecastsImportantly, these approaches use value beyond the GCC, with actionable recommendations applicable to other resource-dependent economies all over the world. The guide's facility is basic: If financial diversity is to succeed, it must move much faster from aspiration to outcomes. The publication sticks out not for presenting novel economic theory, but for firmly insisting that success is less about what a nation chooses to do, and more about how carefully it follows through.
Brunei's decision to focus reform efforts on just two prioritiesEase of Doing Organization and primary educationresulted in remarkable improvements. Qatar's $1B Fund of Funds initiative, utilized to develop a regional equity capital environment in Doha, is highlighted as a model for carrying investment into priority sectors like innovation and healthcare.
The Impact of FDI on GCC Industrial Development
What offers the guide its weight is not just the practical experience behind itSalaytah helped establish the Middle East's first Delivery Unit in Jordan and similar systems in Saudi Arabia and Qatarbut also its timing. Worldwide financial conditions have made diversity not only more immediate, however also harder. As energy markets change and geopolitical tensions increase, the expense of hold-up increases.
Whether GCC governments can shift toward private sector-led development, and do so at scale, remains a challenge. As the guide makes clear, the path forward requires more than huge ideas. It requires what the authors call "ruthless, disciplined delivery."This is not a silver bullet. The downloadable guide below doesn't promise transformation.
Oct 2019 Walid Majdalani, Head of Investcorp Private Equity MENA company, lays out the appealing opportunities of buying GCC Facilities, driven by the area's growth and government initiatives.
Upcoming Middle East Investment Trends for 2026 World Markets
Diversification is accomplish a balanced economy,, Diversification visions and strategies exist. The total Global EDI is composed of tracking.
For non-diversified nations, when cost of the product falls, there is a significant decline in federal government revenue, public costs, bank account balance and global reserves: more volatility. The (including significant commodity exporters, not limited to simply oil) over the, across 25 indications (consisting of three digital signs). The United States And Canada, Western Europe and East Asia Pacific countries top EDI scores for many years.
Despite the fact that structural reforms and diversity efforts undertaken by the GCC impacted MENA's regional scores positively, it still lags five other regional groups., with the top 10 nations having less than a 10-point difference in scores (indicating the strength of diversification)., alongside 4 upper-middle earnings (China, Mexico, Turkey and Thailand) and one lower middle-income country (India, ranked 20th, driven by its services export boom).
Among the e. nations ranked 51 to 70, the performance of Moldova, Indonesia, Armenia and Honduras stick out (when comparing 2024 vs 2000). years, given accelerated diversity strategies of numerous oil-exporting countries. posted a consistent improvement due to a combination of lowered dependence on fuel exports, lowered exports concentration and a modification in the composition of exports.
with oil exporters having the most affordable scores (though specific country-specific efficiency has actually varied gradually). Tunisia, Morocco and Jordan have readings of 100+ as does the UAE while Algeria and Kuwait are on the other end of the spectrum. Throughout all areas, the average score is the for both 2000 and 2024, and the greatest in North America.
Key Factors Shaping Gulf Market Forecasts by 2026
In 2024, the (China was amongst the leading ranked, while Mongolia's score aggravated compared to 2000)., however more to do with a "levelling up" at the bottom rather than an improvement among the top nations. By comparing the (height of the blue box), least variability is seen in South Asia in 2000 and the most in the MENA area (with variation likely driven by the dichotomy within the area in between the resource-heavy states (e.g.

Latest Posts
The 2026 Middle East Fiscal Projection
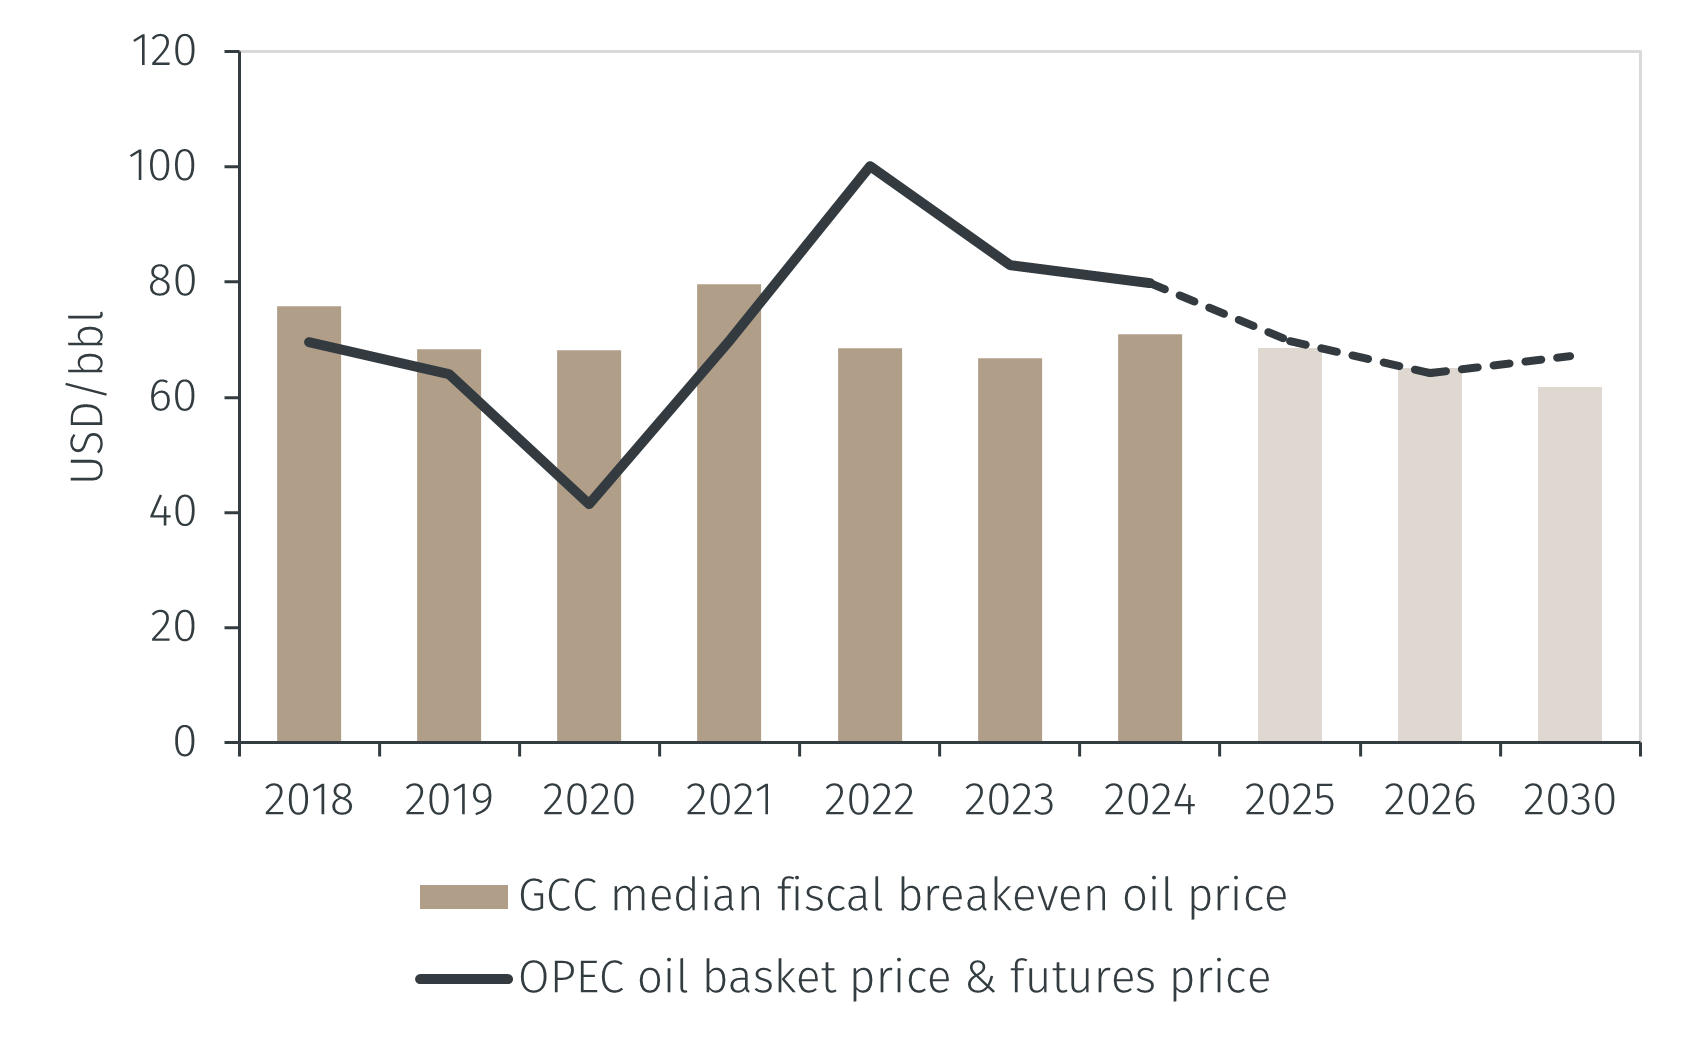
International Capital Opportunities across the Middle East

Can GCC Non-Oil Success Outpace Western Benchmarks?